
Real Estate Investing When Interest Rates Rise: 7 Opportunities
How higher mortgage rates, motivated sellers, and changing market conditions could create opportunities for prepared real estate investors in 2026.
By Jorge Vazquez | CEO & Licensed Real Estate Broker, Graystone Investment Group
Quick Answer: Is It Smart to Invest in Real Estate When Interest Rates Rise?
Rising interest rates can create real estate investment opportunities by reducing buyer demand, increasing seller motivation, and opening the door to discounted properties and creative financing.
However, higher borrowing costs can also reduce rental cash flow and make refinancing more difficult.
The key is to buy below market value, preserve cash reserves, and evaluate properties using today’s financing costs rather than hoping interest rates will decline.
For prepared investors, a challenging real estate market can offer opportunities that were difficult to find when everyone was buying.
Why This Matters for Real Estate Investors in 2026
Something important is happening in the financial markets.
On September 24, 2026, the 10-year U.S. Treasury yield reached 5.18%, while the 30-year Treasury yield climbed to 5.47%.
Freddie Mac also reported that the average 30-year fixed mortgage rate reached 7.03%, up from 6.30% one year earlier. U.S. Department of the Treasury
Why should real estate investors care?
Because when borrowing becomes more expensive, the entire real estate market can change.
Buyers lose purchasing power. Investors become more selective. Some landlords face refinancing challenges. And sellers who previously refused to negotiate may become more flexible.
After more than 25 years investing in real estate, I’ve learned that some of the most interesting opportunities appear when the market becomes uncomfortable.
But there is an important distinction.
A difficult market doesn’t automatically create good deals. It creates conditions where good deals may become available.
Knowing the difference is what separates investing from speculation.
Let’s talk about seven opportunities I would be watching.
1. Rising Interest Rates Can Create Motivated Sellers
When mortgage rates rise, fewer buyers can afford the same properties.
Consider someone shopping for a $300,000 home.
Assuming a 20% down payment and a 30-year mortgage:
| Interest Rate | Monthly Principal & Interest |
|---|---|
| 5% | $1,288 |
| 6% | $1,439 |
| 7% | $1,597 |
| 8% | $1,761 |
Illustrative calculations exclude property taxes, insurance, HOA fees, and other ownership expenses.
At 8%, the buyer pays approximately $473 more per month than at 5%.
That’s over $5,600 in additional annual mortgage payments.
Now imagine thousands of buyers facing similar increases.
Some postpone purchasing. Others reduce their budgets.
Homes may take longer to sell, and some sellers may eventually lower their asking prices.
The Opportunity: Find Sellers Who Need Solutions
I’m particularly interested in landlords who need to sell.
Imagine an investor who owns five rental properties.
Their insurance costs increased. Property taxes went up. Maintenance expenses are higher.
Now one property becomes vacant.
At the same time, the landlord has a loan approaching maturity and needs to refinance.
Suddenly, the property that previously generated positive cash flow may require the owner to contribute money every month.
That investor might decide to sell.
Not necessarily because the property is bad.
They may simply need liquidity, want to reduce debt, or no longer wish to manage the investment.
One investor’s need to exit can become another investor’s opportunity to enter.
However, a motivated seller doesn’t automatically mean a profitable investment.
The purchase price still needs to make sense.
2. Buying Below Market Value Becomes More Important
One of my favorite principles in real estate investing is simple:
You make your money when you buy, not when you sell.
I have repeated this throughout my career because it’s one of the most important lessons investors can learn.
During periods of rapid appreciation, investors sometimes forget this principle.
They purchase properties at retail prices and expect the market to create their profits.
But what happens when property values stop increasing?
What happens when financing becomes more expensive?
Suddenly, the purchase price matters a lot more.
Example: Creating $40,000 in Potential Equity
Consider this hypothetical investment:
| Investment Item | Amount |
|---|---|
| After Repair Value (ARV) | $280,000 |
| Purchase Price | $205,000 |
| Rehabilitation | $35,000 |
| Total Purchase and Rehab | $240,000 |
| Potential Equity Before Other Costs | $40,000 |
The investor has potentially created $40,000 in equity before financing, closing, holding, and other transaction costs.
Now compare that with another investor who purchases the same property for $265,000 and expects appreciation to create their return.
The first investor has a potential equity cushion.
The second investor is depending much more heavily on future market performance.
Neither investment is guaranteed to succeed.
But purchasing below market value gives investors more room to manage unexpected expenses and changing conditions.
My Approach at Graystone
Before we begin searching for properties, I encourage investors to establish a clear buying box.
That means knowing:
- Your target location and property type.
- Your maximum purchase price.
- Your rehabilitation budget.
- Your minimum equity requirement.
- Your expected rental income.
- Your required investment returns.
For more details, read our guide: Rental Property Buy Box for Tampa Real Estate Investors.
The goal isn’t to buy every discounted property.
It’s to buy properties that fit your investment strategy.
3. Cash Buyers Could Gain Negotiating Power
Here’s something interesting about higher interest rates.
While financing becomes more expensive for borrowers, investors with available cash may gain flexibility.
Why?
Because sellers sometimes value certainty as much as price.
Imagine a property owner who has been trying to sell for several months.
They receive two offers.
| Offer A | Offer B |
|---|---|
| $250,000 | $225,000 |
| Conventional financing | Cash |
| Appraisal required | No lender appraisal |
| Financing contingency | No financing contingency |
| Longer closing timeline | Faster closing possible |
Depending on the seller’s circumstances, the cash offer may be attractive.
Of course, cash buyers don’t automatically deserve a discount.
But an investor who can solve a seller’s problem may have more negotiating options.
What About Investors Who Don’t Have Enough Cash?
This is where relationships become valuable.
At Graystone, we work with investors pursuing different financing strategies, including conventional loans, DSCR financing, and private lending.
The objective is to understand your financing options before you find a property.
You don’t want to discover a great opportunity and then begin figuring out how to purchase it.
You want to be financially prepared when the opportunity appears.
4. Seller Financing Could Become More Attractive
Higher interest rates can also create opportunities through creative financing.
One strategy worth understanding is seller financing.
Instead of receiving the entire purchase price at closing, the seller agrees to finance part of the transaction.
The buyer makes payments directly to the seller under negotiated terms.
Consider a hypothetical rental property selling for $250,000.
The seller owns the property free and clear.
They don’t necessarily need all their money immediately. They may prefer receiving monthly income.
An investor could potentially negotiate financing terms that benefit both parties.
Example: Bank Financing vs. Seller Financing
| Financing Terms | Bank Loan | Seller Financing |
|---|---|---|
| Purchase Price | $250,000 | $250,000 |
| Down Payment | $50,000 | $50,000 |
| Loan Amount | $200,000 | $200,000 |
| Interest Rate | 8% | 5.5% |
| Monthly Principal & Interest | $1,468 | $1,136 |
Hypothetical comparison using a 30-year amortization schedule. Seller financing may have shorter repayment periods, balloon payments, or other negotiated terms.
That’s approximately $332 in monthly savings.
Or nearly $4,000 annually.
For a rental property investor, that difference can significantly affect cash flow.
But here’s the part I want investors to understand.
Creative financing doesn’t fix a bad purchase price.
A property that is overpriced at 8% financing may still be overpriced at 5.5%.
The financing structure should improve an already reasonable investment.
Seller-financed transactions also require proper legal documentation, title review, and careful evaluation of repayment obligations.
5. Rental Property Portfolios Could Become Available
This is one of the opportunities I would personally watch closely.
Many landlords who purchased rental properties during periods of lower interest rates now operate in a different environment.
Insurance costs have changed.
Property taxes have increased for some owners.
Repairs are more expensive.
And rental income doesn’t always rise as quickly as operating expenses.
An investor who owns one rental property may be able to absorb a temporary cash-flow shortfall.
But imagine someone who owns 15 or 20 properties.
Several vacancies, major repairs, and refinancing challenges can create a much larger financial problem.
Some owners may eventually decide to sell individual properties or entire portfolios.
What I Would Look For
I would pay particular attention to:
- Retiring landlords.
- Investors reducing debt.
- Owners dealing with expensive repairs.
- Small multifamily properties.
- Rental portfolios with management challenges.
- Properties requiring rehabilitation.
At Graystone, we already work with investors looking for individual rental properties and portfolio acquisitions throughout Tampa Bay and Central Florida.
However, purchasing multiple properties doesn’t automatically make a transaction attractive.
Each property needs to be evaluated individually.
A portfolio with 10 properties can still contain three good investments and seven bad ones.
Never let the size of a transaction distract you from the quality of the underlying assets.
6. Cash Flow Becomes More Important When Appreciation Slows
During strong appreciation cycles, investors sometimes become comfortable purchasing properties that generate little or no immediate cash flow.
They expect property values to increase.
They plan to refinance later.
Or they assume rental income will eventually catch up with expenses.
But what happens when rents remain flat?
What happens when insurance costs increase?
What happens when refinancing becomes more expensive?
This is why I encourage investors to evaluate cash flow and equity together.
The Two Numbers I Watch Closely
At Graystone, one of our preferred initial screening targets for rental acquisitions is an 8% or higher capitalization rate.
The cap rate measures a property’s annual net operating income relative to its value or purchase price, before financing costs.
However, cap rate alone doesn’t tell the whole story.
Investors using financing also need to understand the debt service coverage ratio (DSCR).
Consider this hypothetical example:
| Investment Metric | Amount |
|---|---|
| Annual Net Operating Income | $24,000 |
| Annual Debt Payments | $18,000 |
| DSCR | 1.33 |
| Cash Flow Before Income Taxes and Capital Expenditures | $6,000 |
A DSCR of 1.33 means the property generates approximately $1.33 in net operating income for every $1 of debt payments.
That provides more room to manage unexpected changes than a property barely covering its mortgage.
Don’t Forget Florida’s Hidden Expenses
When analyzing Tampa Bay rental properties, I pay particular attention to:
Property insurance, flood exposure, property taxes, roof condition, HVAC age, maintenance reserves, vacancy, and property management costs.
A property might appear attractive based on purchase price and rental income.
But one unexpected insurance quote or major repair can change the entire investment.
For a deeper explanation, read our article: Top Cash-Flow Strategies Tampa Real Estate Investors Use to Build Reliable Rental Portfolios.
7. Could Higher Interest Rates Create Another 2008 Opportunity?
Whenever the real estate market becomes uncomfortable, someone asks me the same question.
“Jorge, do you think we’re heading toward another 2008?”
I understand why people ask.
I lived through it.
And my experience wasn’t pretty.
I Lost 22 Properties During the 2008 Real Estate Downturn
I was investing aggressively before the housing market collapsed.
Like many investors, I had built a portfolio during a period when financing was widely available and property values were increasing.
Then the market changed.
I lost 22 properties and came close to bankruptcy.
That experience changed the way I approach investing.
It taught me the importance of liquidity, leverage, purchasing below market value, and having a long-term strategy.
I eventually rebuilt my portfolio.
Today, I own approximately 40 properties and continue investing throughout Florida.
But I don’t want investors to misunderstand the lesson.
You don’t need another 2008 to find a good real estate deal.
And you certainly shouldn’t build your investment strategy around hoping for a housing crash.
A significant downturn generally involves more than higher interest rates.
Unemployment, mortgage defaults, forced selling, and credit availability can all influence how a housing market performs.
The better approach is to understand the market in front of you.
Not the market you hope will appear.
Tampa Bay Is Not One Single Real Estate Market
One mistake investors make is treating Tampa Bay as if every neighborhood performs the same way.
A rental property in Dade City may offer different cash-flow potential than a property in South Tampa.
A rehabilitation project in Lakeland may require a different strategy than one in St. Petersburg.
And a property near downtown Tampa may attract a different type of tenant than a home in a suburban neighborhood.
This is why local market knowledge matters.
For more on my investment philosophy, read Tampa Real Estate Investing: Why I Still Believe in This Market After 20+ Years.
Common Mistakes Investors Make When Interest Rates Rise
Higher interest rates can create opportunities, but they can also expose weaknesses in an investment strategy.
Here are five mistakes I encourage investors to avoid.
Mistake #1: Waiting for the Perfect Market
Some investors spend years waiting for interest rates or property prices to reach a specific number.
Meanwhile, they stop evaluating individual opportunities.
You don’t need to purchase a property today.
But you should continue learning, analyzing, and building relationships.
Mistake #2: Assuming Every Discounted Property Is a Deal
A $50,000 price reduction sounds attractive.
But if the property was overpriced by $100,000, it may still be a bad investment.
Focus on market value, not the size of the discount.
Mistake #3: Depending on Future Refinancing
This is particularly important for investors pursuing the BRRRR strategy.
Refinancing can be a valuable tool.
But what happens if rates remain elevated?
What happens if the appraisal comes in lower than expected?
Your investment should have a reasonable path to success even if refinancing takes longer than planned.
Mistake #4: Underestimating Holding Costs
Higher interest rates can make rehabilitation projects more expensive.
Every additional month of ownership may mean more interest, insurance, taxes, utilities, and other expenses.
A flip that looked profitable on paper can quickly lose its margin when the project takes longer than expected.
Mistake #5: Using All Your Available Cash
I learned this lesson the hard way.
Buying below market value is important.
But maintaining liquidity is equally important.
You need reserves for vacancies, repairs, emergencies, and unexpected opportunities.
Don’t become so focused on acquiring your next property that you put your existing portfolio at risk.
My 5-Step Strategy for Investing When Interest Rates Rise
If I were preparing to acquire another rental property in today’s environment, I would focus on five things.
| Step | What I Would Do |
|---|---|
| 1. Establish a Buying Box | Define location, price, rehab, equity, and return requirements. |
| 2. Secure Financing | Understand conventional, DSCR, and private lending options. |
| 3. Preserve Liquidity | Maintain reserves for repairs, vacancies, and unexpected costs. |
| 4. Build Relationships | Connect with agents, wholesalers, lenders, contractors, and property managers. |
| 5. Analyze Conservatively | Use realistic rents, current financing costs, and appropriate expense reserves. |
The objective isn’t necessarily to buy more properties.
It’s to acquire properties that support your long-term investment goals.
Frequently Asked Questions About Real Estate Investing When Interest Rates Rise
Is it better to buy real estate when interest rates are high or low?
Lower rates generally reduce borrowing costs, but they can also increase buyer competition. Higher rates make financing more expensive but may create opportunities to negotiate lower purchase prices.
The right decision depends on the individual property, financing terms, and investment strategy.
Do property prices always fall when interest rates rise?
No. Higher rates can reduce buyer demand, but property prices also depend on housing supply, employment, population growth, and local market conditions.
Can you still make money with rental properties at 7% or 8% interest rates?
Yes, some properties can generate positive cash flow at those rates. However, investors need to evaluate purchase price, rental income, operating expenses, and financing costs carefully.
Is cash better than financing when interest rates rise?
Cash can provide negotiating flexibility and eliminate mortgage interest expenses. Financing allows investors to preserve capital and potentially acquire more properties.
Neither approach guarantees a better return.
Should investors wait for mortgage rates to fall before buying?
Waiting may be appropriate for some investors. Others may find properties that meet their goals under current conditions.
The key is to avoid purchasing a property that only works if future interest rates decline.
Final Thoughts: You Don’t Need a Housing Crash to Find a Great Deal
After more than 25 years investing in real estate, I’ve seen people make money in strong markets, weak markets, and everything in between.
I’ve also seen investors lose money during periods when everyone else seemed to be getting rich.
The difference often comes down to preparation, discipline, and purchasing at the right price.
Higher interest rates create challenges.
But those challenges can also create opportunities.
A landlord facing refinancing difficulties may need a buyer.
A property requiring substantial repairs may need an experienced investor.
A seller who wants monthly income may be open to creative financing.
And an investor with available capital may be able to purchase a property that previously wasn’t available at an acceptable price.
Here’s what I want you to remember:
You don’t need to predict the next real estate crash. You need to be prepared when the right opportunity comes along.
That’s the philosophy we’ve built around at Graystone Investment Group.
We help investors find properties, evaluate opportunities, arrange financing, manage rehabilitation, and operate rental portfolios throughout Tampa Bay and Central Florida.
Because successful real estate investing isn’t simply about buying properties.
It’s about building a strategy that works through changing market conditions.
You invest. We do the rest.
— Jorge Vazquez
CEO & Licensed Real Estate Broker
Graystone Investment Group
Ready to Find Your Next Investment Property?
Whether you’re purchasing your first rental or expanding an existing portfolio, Graystone Investment Group can help you identify opportunities that align with your financial goals.
Our team works with investors seeking off-market properties, rental acquisitions, rehabilitation projects, and portfolio purchases throughout Tampa Bay and Central Florida.
The next opportunity might not come from a rising market. It might come from a seller who needs a solution.
Schedule a Consultation With Jorge Vazquez
Sources & Additional Reading
Official Market Data
- U.S. Department of the Treasury — Daily Treasury Yield Curve Rates
- Freddie Mac — Primary Mortgage Market Survey
Additional Graystone Investment Resources
- Rental Property Buy Box for Tampa Real Estate Investors
- Top Cash-Flow Strategies Tampa Real Estate Investors Use to Build Reliable Rental Portfolios
- Tampa Real Estate Investing
WordPress SEO Settings
| Field | Recommended Content |
|---|---|
| SEO Title | Real Estate Investing When Interest Rates Rise |
| Focus Keyword | Real estate investing when interest rates rise |
| URL Slug | real-estate-investing-when-interest-rates-rise |
| Meta Description | Discover 7 real estate investment opportunities when interest rates rise, from motivated sellers to discounted rentals and creative financing. |
| Image Alt Text | Real estate investing when interest rates rise in Tampa Bay |
| Secondary Keywords | Rising mortgage rates, motivated sellers, Tampa real estate investing, rental property investing, seller financing, distressed properties |
Suggested featured image concept: A dramatic split-screen showing storm clouds over the financial markets on one side and sunlight breaking through over Tampa rental properties on the other. A subtle upward Treasury yield chart contrasts with a discounted house and a key in the foreground.
Featured image headline:
WHEN INTEREST RATES RISE, OPPORTUNITIES CHANGE.
Book an Expert
New investor? Start with Jorge.
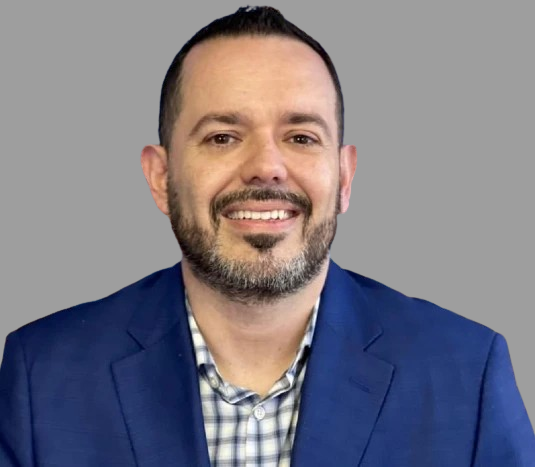
Jorge Vazquez – CEO & Investment Strategist at Graystone. Let’s make your portfolio stronger, steadier, and more profitable.
Deals? Book with Cody.
Meet Cody Bergstrom, Your Expert in Finding Deals Let’s find an off-market deal that actually works for you.
Need financing? Book with Lisa.
Meet Lisa Kaye Price, the LendingGig Top ML Let’s figure out the smartest way to fund your next deal.
Looking for PM? Book with Jay
Jay Michalec – COO & Property Management Expert at Graystone. Let’s make your rentals easier, calmer, and more profitable.