
By Jorge Vazquez, CEO, Graystone Investment Group
Over my 20-plus years in real estate—completing more than 3,500 transactions and building a personal portfolio of over 40 properties—the single most common question investors ask me is: "What is a good return on real estate investment?"
The short answer? For most residential rental properties, a 8% to 12% cash-on-cash return is widely considered a good benchmark, while a total return (cash flow + appreciation + debt paydown) of 15% to 20%+ is excellent.
However, if you ask five different investors what a "good" return is, you'll get five different answers. That is because "good" depends entirely on your investment strategy, how much leverage you use, and whether you are playing for immediate cash flow or long-term wealth creation.
Let's break down how to evaluate returns like a pro, what benchmarks you should aim for, and how to avoid the common math traps that trip up new investors.
Benchmark Returns by Strategy: What to Aim For
When evaluating deals at Graystone Investment Group, we don't look at returns in a vacuum. A 6% return on a stabilized property in a booming growth market like Tampa Bay might be a far better deal than a 15% "paper return" on a high-risk property in a declining neighborhood.
Here is what realistic, "good" returns look like across different real estate strategies:
| Investment Strategy | Metric Used | Target Benchmark for a "Good" Return |
| Buy-and-Hold Rentals (Financed) | Cash-on-Cash Return | 8% – 12%+ |
| All-Cash Rental Purchases | Cap Rate (Capitalization Rate) | 6% – 8%+ |
| Fix and Flip | Return on Capital / Profit | 15% – 20%+ per project |
| BRRRR Strategy | Cash-on-Cash Return | 15% to Infinite ROI (when capital is fully refinanced out) |
| Overall Wealth Strategy | Total Annual Return | 15% – 25%+ (Cash flow + Appreciation + Debt Paydown) |
The 3 Ways to Measure Real Estate Returns
To understand what is a good return on real estate investment, you must first know which return formula you are calculating. Investors who get into trouble usually confuse these three metrics:
1. Cash-on-Cash Return (The Cash Flow Metric)
This measures the actual cash profit you pocket each year relative to the total cash you invested out of pocket (down payment, closing costs, and rehab).
$$\text = \frac \times 100$$
-
What is good? 8% to 12%. If you put down $50,000 in total cash and net $5,000 per year after paying all expenses and the mortgage, you are at a 10% cash-on-cash return.
2. Cap Rate (The Pure Asset Yield)
Capitalization rate measures the property's unlevered yield—meaning how much profit the property generates if you paid 100% cash with no mortgage.
$$\text = \frac \times 100$$
-
What is good? 6% to 8% in growing metropolitan markets. Higher cap rates (10%+) usually signal higher tenant default risk, older building infrastructure, or stagnant neighborhood growth.
3. Total Return (The Wealth Multiplier)
While cash flow buys day-to-day freedom, equity builds true generation-defining wealth. Total return combines three profit engines:
-
Net Cash Flow (Money in your bank account)
-
Mortgage Paydown (Tenants paying off your principal balance)
-
Market Appreciation (Property increasing in value over time)
$$\text = \frac \times 100$$
-
What is good? 15% to 25%+ annually. A property making 8% cash-on-cash can easily generate a 20%+ total return once you factor in loan amortization and moderate 3–5% appreciation.
4 Common Traps That Distort Real Estate ROI
When investors fail to achieve a good return on real estate investment, it is rarely because the market failed—it is usually because their initial math was incomplete. Watch out for these four traps:
-
Ignoring Vacancy and Reserves: Never assume 100% occupancy or zero repairs. Always budget 5%–8% for vacancies and set aside reserves for maintenance and capital expenditures (roof, HVAC, water heater).
-
Chasing Pro Forma Fantasy Numbers: Sellers often present "pro forma" projections based on hypothetical rents. Always underwrite deals using actual market comps and verified current rents.
-
Confusing Gross Yield with Net Return: A property bringing in $2,000/month on a $150,000 purchase price looks like a 16% gross return, but after property taxes, insurance, management, and repairs, the actual net yield could drop by half.
-
Over-Improving the Property: Pumping $30,000 worth of luxury renovations into a working-class rental will not yield a proportional return. Match your rehab budget to local neighborhood standards to maximize the principle of contribution.
The Graystone Takeaway
At the end of the day, a "good" return is one that aligns with your financial goals without forcing you into excessive risk.
Cash flow buys freedom today, while equity builds wealth for tomorrow. If you maintain disciplined underwriting, run conservative worst-case scenarios, and focus on growth submarkets with strong rental demand, achieving double-digit returns is completely achievable.
Keep it consistent, stay patient, stay true—if I did it, so can you.
Helpful Resources & Internal Links
-
How to Calculate Return on Investment in Real Estate – Read my step-by-step breakdown of ROI formulas, cash-on-cash examples, and how to calculate infinite ROI using the BRRRR method.
-
Essential Questions First-Time Investors Should Ask – Discover how rent-to-price ratios in Tampa Bay create cash flow opportunities and how to select the right asset class.
-
Graystone Agency Rentals & Turnkey Property Management – Learn how $0 tenant placement fees and turnkey management preserve your bottom-line investment returns.
-
Investopedia: How to Calculate ROI on Rental Property (External Resource) – An in-depth external guide on real estate ROI calculation methods, cash vs. leveraged scenarios, and property valuation standards.
Book an Expert
New investor? Start with Jorge.
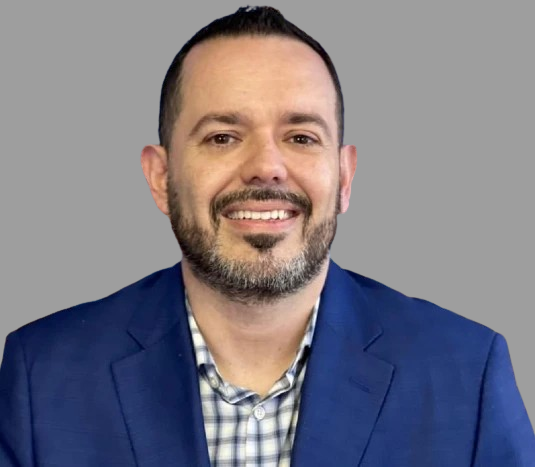
Jorge Vazquez – CEO & Investment Strategist at Graystone. Let’s make your portfolio stronger, steadier, and more profitable.
Deals? Book with Cody.
Meet Cody Bergstrom, Your Expert in Finding Deals Let’s find an off-market deal that actually works for you.
Need financing? Book with Lisa.
Meet Lisa Kaye Price, the LendingGig Top ML Let’s figure out the smartest way to fund your next deal.
Looking for PM? Book with Jay
Jay Michalec – COO & Property Management Expert at Graystone. Let’s make your rentals easier, calmer, and more profitable.