
By Jorge Vazquez
CEO & Founder, Graystone Investment Group
After more than 20 years in the business, I’ve learned that the best investors are rarely the ones chasing the flashiest deal. They’re the ones who understand the numbers, know their strategy, and stay disciplined when everyone else gets emotional.
Right now, with traditional mortgage rates creating friction for both buyers and sellers, one financing strategy has consistently separated active dealmakers from frustrated onlookers: seller financed real estate.
When bank lending tightens or interest rates rise, waiting around for conventional institutional loans can sink a great opportunity. Seller financing—also known as owner financing—flips the script by allowing the property owner to act as the lender. If you want to scale your portfolio, structure win-win transactions, and acquire cash-flowing properties regardless of market conditions, you need to understand how seller financed real estate works from the inside out.
What Is Seller Financed Real Estate?
In a standard real estate transaction, a buyer brings a cash down payment and secures a loan from a bank or mortgage company to pay off the seller. The seller walks away with their cash, and the buyer makes monthly principal and interest payments to the financial institution.
With seller financed real estate, the bank is completely removed from the transaction. The buyer and seller enter into a direct agreement where the buyer makes monthly installment payments directly to the seller based on agreed-upon terms—including purchase price, interest rate, down payment, and repayment duration.
The seller retains a security interest in the asset (typically secured via a promissory note and mortgage or deed of trust), while the buyer gains equitable title, rights of possession, and operational control of the real estate.
Key Structures in Owner-Financed Transactions
Not every seller-financed deal is built the same way. Depending on whether the seller owns the property free and clear or carries an existing loan, several structures can be utilized:
- Classic Installment Sale (Free and Clear): The simplest form of owner financing. The seller owns the property outright, title transfers to the buyer at closing, and the buyer pays the seller fixed monthly payments over an agreed timeline.
- Wraparound Mortgage: Used when the seller has an existing underlying mortgage. The seller creates a new loan for the buyer at a higher wrap rate. The buyer pays the seller, and the seller continues servicing their original mortgage while keeping the interest spread.
- Subject-To Financing: The buyer takes over payments on the existing underlying mortgage while receiving the property deed. The original loan stays in the seller’s name, making this a common strategy for acquisition without new bank qualifying.
- Seller Second Mortgage: The buyer secures primary funding from an institutional lender or private investor, and the seller carries back a secondary note to cover a portion of the down payment or purchase gap.
Why Sellers Agree to Act as the Bank
Investors often ask me: “Jorge, why would a property owner agree to carry paper instead of taking cash?” The reality is that seller financing frequently solves major problems for owners that a traditional cash buyer cannot:
- Tax Deferral (Installment Sale Tax Treatment): Selling a property for a lump sum cash payout can trigger immediate capital gains tax liability. Carrying a note spreads capital gains exposure over multiple tax years as principal is received.
- Passive Monthly Income: Many retired real estate owners want to step away from property management, tenant calls, and maintenance without sacrificing cash flow. Carrying a note converts active rental headaches into predictable monthly yield.
- Higher Purchase Price & Interest Yield: Sellers offering financing can often command top-market pricing and earn competitive interest rates on their capital, far exceeding traditional savings or yield vehicles.
- Faster, Cleaner Closings: Eliminating bank underwriting, strict appraisal guidelines, and corporate loan processors allows deals to close in weeks rather than months.
How Investors Use Seller Financing to Scale
For real estate investors, seller financed real estate provides flexibility that traditional institutional mortgages simply cannot match. You can negotiate custom down payments, deferred payment periods during property renovations, interest-only payments, or balloon payment timelines aligned with your value-add plan.
By leveraging creative financing strategies alongside disciplined underwriting, you can preserve capital, increase cash-on-cash returns, and build a resilient portfolio across any market cycle.
— Jorge Vazquez
CEO of Graystone Investment Group
Internal Resources & References
- Learn the exact operational mechanics and note structures in our article on What Is Seller Financing in Real Estate?
- Explore advanced acquisition structures with our breakdown on Wraparound Mortgages in Tampa
- Understand how to evaluate creative acquisition returns in Real Estate Investment Analysis: How to Know If a Deal Is Actually Worth It
External Resource
- Learn more about how installment sales affect tax liabilities on the official IRS Installment Sales Guidelines (Topic No. 705).
Book an Expert
New investor? Start with Jorge.
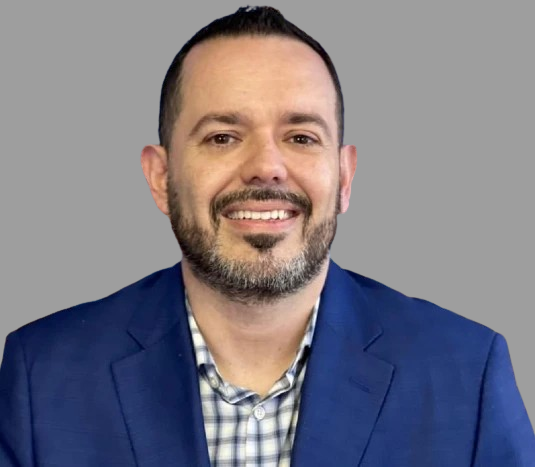
Jorge Vazquez – CEO & Investment Strategist at Graystone. Let’s make your portfolio stronger, steadier, and more profitable.
Deals? Book with Cody.
Meet Cody Bergstrom, Your Expert in Finding Deals Let’s find an off-market deal that actually works for you.
Need financing? Book with Lisa.
Meet Lisa Kaye Price, the LendingGig Top ML Let’s figure out the smartest way to fund your next deal.
Looking for PM? Book with Jay
Jay Michalec – COO & Property Management Expert at Graystone. Let’s make your rentals easier, calmer, and more profitable.