
Many first-time investors come to Tampa with the same challenge: they know they want rental property, but they aren’t sure which questions to ask before committing to anything. The term “real estate” gets used loosely across listings, platforms, and conversations, but for an income-focused buyer, it means something specific. It means assets that pay you every month, not just properties that appreciate over time. If you’re evaluating real estate in Tampa, the questions you ask before you make an offer will determine whether the deal performs or bleeds cash.
Tampa stands out in 2026 as a market where the math on rental income still works. Strong job growth, consistent population inflows, and a tenant base that keeps vacancy low make it genuinely compelling. Average rent across tracked Tampa ZIP codes sits around $2,006 per month, while home values in some investor-friendly corridors remain below the national median. That gap is where returns come from. The market rewards investors who ask the right questions upfront, skipping them is how people end up with properties that look fine on paper but underperform in practice.
This article walks you through what to ask, and why the order matters.
What does “real estate” actually mean for an income-focused buyer?
For a homebuyer, a property is somewhere to live. For an income investor, a property is measured by what it produces each month after expenses. The question isn’t “Do I love this house?” It’s “What does this property net after taxes, insurance, maintenance, and management?” That single shift in perspective changes every decision that follows, from which neighborhoods you target to what price range makes sense.
Tampa’s rent-to-price ratio creates genuine cash-flow opportunity in submarkets where other coastal markets have long since priced out the returns. When the numbers work in your favor, you’re not speculating on appreciation. You’re buying an income stream that happens to sit on land that also appreciates. Investors who get into trouble here are typically the ones who lead with appreciation assumptions and treat rent as an afterthought.
Which property type fits your investment goals?
Single-family homes are where most first-time investors start, and there are good reasons for that. They attract longer-tenancy renters, qualify for conventional financing, and are straightforward to manage. In Tampa’s suburban growth corridors, including Brandon, Riverview, and Wesley Chapel, vacancy rates for single-family rentals run between 5% and 7% based on current submarket tracking, which means strong occupancy when the property is priced correctly. The tradeoff is simple: one vacancy means zero income until it’s filled.
Small multifamily properties, duplexes to fourplexes, reduce that risk because one empty unit doesn’t wipe out your entire monthly return. Financing is slightly more complex, but the cash-flow math often works out better on a per-dollar-invested basis. As Tampa’s population density increases, inner-neighborhood multifamily has seen strong rent growth, and these assets tend to hold value well across market cycles.
Turnkey properties come renovated, leased, and managed from day one. For out-of-state buyers, this model removes the operational setup entirely. The premium you pay is real, turnkey sellers typically price in a 10% to 30% markup over comparable distressed inventory. But so is the value: no renovation surprises, no tenant sourcing delay, and no coordinating contractors from across the country. The critical thing is that you don’t pay the turnkey premium without disciplined underwriting behind it. Convenience costs money. Make sure you know exactly what you’re buying.
How do you evaluate cash flow on Tampa real estate before making an offer?
Cash flow analysis is straightforward once you know which inputs to use. Before committing to any Tampa investment property, you need five numbers: gross monthly rent at current market rate, a vacancy allowance of 6% to 8% (a conservative assumption consistent with Tampa submarket performance), operating expenses including taxes and insurance, a maintenance reserve of roughly 8% to 10% of rent, and property management fees typically running 8% to 10%. What’s left after those deductions is your net monthly income. If the number is negative or too thin to absorb a single bad month, the deal doesn’t work, regardless of how the property looks.
Insurance deserves special attention in Tampa. Landlord property insurance for a typical single-family rental runs $2,300 to $3,000 per year for stabilized, non-coastal properties. For older frame construction, homes near the coast, or properties in flood zones, quotes can reach $3,500 to $6,000 or higher. That range is large enough to swing a marginal deal from positive to negative. Underwrite insurance at the high end of the range, then add a 10% to 20% cushion for renewals. Florida carriers can reprice or non-renew quickly, and that risk is real operating exposure, not a one-time closing cost.
Conservative underwriting also means you don’t use best-case rent projections. Use current comparable leases in that specific submarket, not averages across the entire city. Tampa cap rates for Class B properties run roughly 5.8% to 6.8%, with value-add opportunities reaching 7% to 8.5% or higher. Know which category you’re buying before you submit an offer.
What should you ask about property condition and management?
A property that looks rent-ready can hide tens of thousands of dollars in deferred maintenance. Roof condition, HVAC age, plumbing configuration, and foundation status are the four categories that kill deals after closing when they aren’t reviewed before. A third-party inspection, not just a walk-through, is the only way to price that risk accurately. Buyers who skip this step on turnkey properties because they assume “move-in ready” means “problem-free” often learn an expensive lesson in year two.
The management question most investors forget to ask is this: who runs the property after closing, and what does their actual portfolio look like? Management quality is the single biggest variable in whether a rental performs on paper versus in practice. An in-house team that already operates hundreds of units in Tampa has meaningful data on local tenant behavior, maintenance costs, and vendor pricing, the kind of depth that typically comes with managing at scale. That difference tends to show up in vacancy rates, repair costs, and tenant retention over time.
You should also ask how the listing data was sourced and verified. Cross-check addresses independently, confirm property ownership through county assessor records, and make sure the rent projections you’re given are based on actual comparable leases in the submarket, not ZIP-wide or metro-wide averages. A focused review like this takes very little time. Skipping it can cost you years of underperformance.
How does Graystone Investment Group serve Tampa real estate investors from start to finish?
Graystone Investment Group handles every stage of the investment process under one roof. The firm sources properties, coordinates financing, applies conservative underwriting standards, and manages day-to-day operations through its in-house property management division, which currently oversees more than 300 rental doors across the Tampa market. For a first-time investor or an out-of-state buyer, that single point of contact removes the coordination friction that causes most deals to stall or go sideways.
Every property Graystone presents goes through a third-party inspection before it’s approved for investor consideration. Those inspection reports, along with underwriting assumptions and neighborhood data, are uploaded to a shared Diligence Vault, a transparency tool that gives investors access to the same documentation the firm uses internally. Jorge Vazquez, who has led the firm through more than 3,500 transactions over 20 years, built this process specifically because most first-time investors don’t know what they don’t know. The vault closes that information gap before money changes hands.
The firm’s cash-flow-first philosophy means returns are built on real market data and conservative assumptions, with appreciation treated as upside rather than a requirement. That approach matters most when insurance costs spike, a vacancy runs long, or a repair comes in over budget. The floor of what a property produces is more important than the ceiling, and Graystone’s underwriting is built around that principle.
What are the right next steps once you’ve done your homework?
In Tampa’s investor market, the best deals move fast. Being pre-qualified for investment financing before you identify a property isn’t optional, it’s the difference between closing and watching someone else close. Investment property loans have different requirements than primary residence mortgages: higher down payments, debt-service coverage ratio checks, and sometimes different rate structures. Knowing your financing ceiling upfront anchors your underwriting to a realistic price range and keeps you from committing to a deal you can’t actually close.
The process is manageable once you have the right partner in place. Here’s how it typically flows:
- Identify your target return and investment range
- Review sourced properties with full diligence documentation
- Run the cash-flow numbers using current Tampa market inputs
- Confirm the management plan for post-closing operations
- Proceed to contract
For out-of-state investors working with Graystone, the entire sequence from first conversation to lease-up is designed to be handled remotely, with no flight to Tampa required.
If you’re ready to move from research to action, reach out to the Graystone Investment Group team directly. The first conversation is about understanding your goals, not pushing a property. That’s how the firm has operated for 20 years, and it’s why investor relationships here tend to run through multiple deals rather than stopping after one.
The questions that separate investors from speculators
First-time investors who ask the right questions before buying consistently outperform those who lead with emotion or move on incomplete data. The questions are straightforward: What does this property produce net? What are the condition risks? Who manages it and what does their track record actually look like? Is my underwriting conservative enough to survive a bad month?
Tampa’s rental real estate market in 2026 offers real opportunity, but no market compensates for a bad deal. The investors who win here treat every property as a business decision and partner with people who have the data to back their recommendations. Whether you’re buying your first rental door or adding to an existing portfolio, the framework is the same. Start with the numbers, verify the condition, and make sure the people managing the asset know Tampa the way it needs to be known.
Book an Expert
New investor? Start with Jorge.
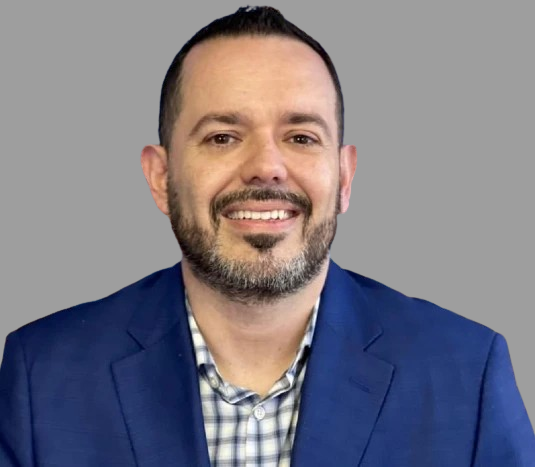
Jorge Vazquez – CEO & Investment Strategist at Graystone. Let’s make your portfolio stronger, steadier, and more profitable.
Deals? Book with Cody.
Meet Cody Bergstrom, Your Expert in Finding Deals Let’s find an off-market deal that actually works for you.
Need financing? Book with Lisa.
Meet Lisa Kaye Price, the LendingGig Top ML Let’s figure out the smartest way to fund your next deal.
Looking for PM? Book with Jay
Jay Michalec – COO & Property Management Expert at Graystone. Let’s make your rentals easier, calmer, and more profitable.