
Most investors reach a point where the stock market feels like a slot machine and public REITs start moving in lockstep with everything else they already own. The appeal of real estate is obvious: tangible assets, rental income, and something you can actually control. But when people say “real estate investing,” they often lump together strategies that have almost nothing in common. Buying a rental property outright, putting money into a publicly traded REIT, and investing in a private real estate fund are three fundamentally different decisions with different risk profiles, tax treatments, liquidity terms, and return expectations. Many investors eventually consider private real estate investment as an alternative to stocks and public REITs, and for good reason.
Direct real estate investment through private vehicles is its own category, and it requires a different kind of analysis than picking a stock ticker. Private deals can deliver strong, predictable cash flow, but only when they’re evaluated with discipline. This article gives you a clear definition of private real estate investing, an honest comparison against REITs and stocks, a breakdown of what each strategy actually pays, and a practical due diligence framework you can apply to a real deal. Firms like Graystone Investment Group in Tampa have built full-service platforms around exactly this kind of conservative underwriting and operational transparency, more on how that works in practice toward the end.
What private real estate investment actually means
The most important distinction in this space is simple: public real estate trades on exchanges, and private real estate doesn’t. When you buy shares in a publicly traded REIT or a real estate ETF, the price updates every second the market is open, institutional pricing is already baked in, and you can exit in minutes. Private property investments work differently. You’re owning an asset directly or holding a stake in an unlisted vehicle with no daily price discovery. There’s no ticker telling you what your investment is worth on any given Tuesday.
That absence of mark-to-market pricing functions as a feature for long-term investors, not a flaw. Research in behavioral finance suggests that daily price visibility tends to increase short-term trading and investor anxiety, removing that noise can support more disciplined, long-horizon decision-making. The trade-off is straightforward: lower volatility on paper, but real illiquidity when you need to exit.
The four main vehicles for accessing private real estate investment
Investors access private real estate through four primary structures, each carrying different fees, control levels, and liquidity terms. Understanding which structure fits your capital, involvement preference, and liquidity timeline is the prerequisite to evaluating any individual deal.
- Direct ownership:single-family or small multifamily properties. Full control, full operational responsibility, and no intermediary fees beyond standard transaction costs.
- Private real estate funds:closed-end or open-end structures with pooled capital managed by a professional GP, includingprivate equity real estate vehiclesand institutional real estate funds. Minimum investments vary widely, mid-market funds often start at $50,000, $250,000, while institutional-grade closed-end funds typically require $250,000 to $1 million or more.
- Non-traded REITs and private REITs:lower minimums ($1,000 to $25,000 for retail products), broader access, but often complex fee layers and limited redemption rights.
- Syndications and crowdfunding platforms:deal-by-deal co-investment, typically requiring $25,000 to $100,000 per project, with returns tied directly to a single asset’s performance.
Who qualifies and what capital you actually need
Eligibility depends on which structure you’re targeting. Accredited investor status requires a net worth above $1 million excluding your primary residence, or individual income above $200,000 per year for the past two years ($300,000 combined with a spouse). That threshold gates access to most syndications and many private funds. The stricter qualified purchaser standard, which requires $5 million in investable assets, opens the door to certain institutional-grade closed-end real estate funds that don’t accept standard accredited investors.
On the capital side, retail non-traded REITs can start as low as $1,000 to $25,000. Mid-market private funds and syndications typically require $50,000 to $250,000. Traditional closed-end private equity real estate funds often start at $250,000 and can require $1 million or more. Knowing your tier before you start evaluating deals saves significant time.
Private real estate investment returns vs. REITs and stocks
Return comparisons between asset classes are only useful when they account for the full picture: fees, taxes, liquidity, and actual cash flow. Private real estate funds targeting core strategies average 8, 9% net IRR; core-plus runs 10, 11%; value-add targets around 15%; and opportunistic strategies aim for 18% or more. According to NAREIT data, public REITs have returned approximately 7, 10% annually in total over extended periods, but they carry significant stock market correlation. When equities sell off, REITs typically follow. Stocks offer higher growth potential but no asset control, no depreciation benefit, and no direct rental income stream.
For passive income investors who want predictable monthly cash flow rather than speculative appreciation, the core and core-plus end of the private real estate market typically outperforms on a risk-adjusted basis. The caveat is that those returns only materialize when the deal is correctly underwritten and the operations are managed with discipline.
What you give up for higher potential returns
Liquidity is the real cost of private real estate investing, and investors need to understand it precisely before committing capital. Closed-end private funds typically run 8, 10 years, with capital called progressively over the first 3, 5 years and no ordinary redemption right during that window. Syndications and value-add funds typically lock up capital for 3, 7 years. There’s generally no public secondary market, and any early exit depends on finding a buyer for your LP interest privately, often at a discount.
Fees add another layer that must be modeled into return expectations. Management fees run 1, 2% annually, usually charged on committed capital during the investment period and on invested capital or NAV afterward, a common structure documented across industry fund surveys. Carried interest of 20% above an 8% preferred return is widely cited as the industry standard for closed-end fund waterfalls. Acquisition fees of 0.5, 1.5% of deal value are common, with some managers also charging a disposition fee on the sale, though institutional deals often negotiate these away. Those costs compound across a 10-year fund life and can meaningfully reduce the net return if you don’t account for them upfront.
Tax advantages that separate private property investments from stocks and REITs
This is where private real estate investment creates a genuine structural edge. Depreciation on residential rentals over 27.5 years creates a non-cash deduction that often offsets most of your taxable rental income in the early years of ownership. A 1031 exchange lets you roll gains from one investment property into another like-kind property and defer capital gains tax indefinitely, compounding equity without a tax drag at each exit. Holding through an LLC or partnership passes income and losses directly to your tax return, avoiding the corporate-level double taxation that shareholders in C-corps absorb.
Cost segregation takes the tax efficiency further. By reclassifying components of a property, appliances, flooring, landscaping, certain fixtures, into 5-, 7-, or 15-year depreciation schedules instead of the standard 27.5-year building schedule, investors can accelerate deductions in the early years. On a $300,000 residential rental, reclassifying 20, 35% of the depreciable basis and applying bonus depreciation can generate $19,000 to $38,000 in first-year tax savings depending on your marginal bracket, assuming land is excluded from the depreciable basis and current bonus depreciation rules apply. That’s real money that compounds when reinvested.
The four private real estate strategies and what they actually pay
Core and core-plus: the cash-flow-first approach
Core assets are stabilized, occupied properties in strong markets with predictable income and low operational complexity. They deliver the highest current cash yield among private real estate strategies and the lowest volatility, targeting 8, 9% net IRR. Core-plus adds a modest value-creation component through light improvements or lease optimization, targeting 10, 11% IRR while still generating income from day one. These two strategies are the most practical starting point for passive income investors and out-of-state buyers who want predictable distributions and can’t tolerate a long period with no income while a repositioning plays out.
The returns on core and core-plus depend less on a successful turnaround and more on the quality of operations from the moment you close. Day-to-day factors, tenant retention rates, maintenance response times, lease renewal execution, directly determine whether pro forma cash flow becomes actual cash flow. That’s why in-house property management is such a differentiator in this part of the market.
Value-add and opportunistic: when the upside is further out
Value-add deals involve renovation, lease-up, or repositioning underperforming assets. Initial cash yields are lower because capital is tied up in improvements, but target IRRs around 15% reflect the upside if execution goes well. Opportunistic strategies, including development, distressed acquisitions, and major redevelopment, target 18% or more in IRR but carry the most execution risk and the longest path to any distribution.
Investors pursuing private real estate for passive income need to understand that value-add and opportunistic returns are heavily back-ended. The income comes at the end, not throughout the hold period. These strategies require a manager with a proven track record of completed exits, not just a compelling pitch deck showing projected returns.
How private real estate investment generates passive income: a step-by-step framework
The underwriting checklist every investor should run
Conservative underwriting starts with market rent benchmarked against actual comparable units, not the seller’s optimistic pro forma number. From there, every investor should run the same set of inputs before trusting any projected return.
- Vacancy rate:use 8, 10% for conservative underwriting, not the 3, 5% figures common in seller-provided pro formas
- Operating expenses:property taxes, insurance, maintenance, property management fees (8, 10% of gross rent is a common benchmark for single-family and small multifamily outsourced management), and a capital expenditure reserve of at least 5, 8% of gross rents
- Net operating income (NOI):gross income minus all operating expenses, before debt service
- Debt service coverage ratio (DSCR):at least 1.2x as a conservative benchmark, this confirms meaningful cash flow cushion above the mortgage payment even if income dips slightly, and aligns with thresholds commonly used by lenders and underwriters
- Cap rate:compared to local market data to assess whether the purchase price reflects actual asset value
Cash-on-cash return equals annual cash flow divided by total cash invested, including down payment, closing costs, and initial repairs. In Tampa’s current market, a well-underwritten single-family rental typically lands in the 5, 6% cash-on-cash range based on 2026 market data. Deals projecting 8% or higher with optimistic assumptions deserve scrutiny before they deserve your capital.
Reading a pro forma with the right skepticism
Two red flags appear in seller-provided pro formas more than any others. The first is a vacancy assumption below 5%, which ignores real turnover time, lease-up periods, and periodic problem tenants. The second is a missing capex reserve line, which treats the property as if it will never need a roof, HVAC system, water heater, or appliance replaced. Both omissions will erase projected returns in the real world, usually within the first two years.
Beyond those two, watch for rent growth assumptions that exceed local market trends year over year, exit cap rate assumptions that imply you’ll sell at a meaningfully lower cap rate than you purchased without a defensible reason, and operating expense ratios that look suspiciously low compared to comparable properties. If a deal requires multiple optimistic assumptions working simultaneously to generate its projected return, the projected return is inflated.
Due diligence questions to ask before committing capital
These are the specific questions that separate disciplined investors from ones who rely on a sponsor’s marketing materials. Ask for the actual trailing 12-month income and expense statements, not just a projected pro forma. Request the third-party inspection report and find out who commissioned it. Ask what the property manager’s current vacancy rate is across comparable units in the same submarket. Ask what deferred maintenance exists and how the sponsor plans to fund it. Finally, ask how sensitive the returns are if the exit assumption shifts by 10%: if the deal falls apart under a mild stress test, it doesn’t belong in a conservative portfolio.
How Graystone Investment Group vets Tampa rental properties
Graystone Investment Group applies this exact framework and then adds a layer that many sponsors skip entirely. Every property the firm presents to investors undergoes a third-party inspection before approval, with all findings made available for investors to review directly before committing capital. Investors see the full picture, including repair exposure, deferred maintenance, and any system approaching end of life, not just a summary of findings.
Underwriting inputs at Graystone are conservative by design: sustainable rent, not top-of-market projections, and real vacancy data from the local Tampa market rather than aspirational numbers from a seller’s broker. As one illustration of this approach, a Tampa single-family rental under review showed a seller pro forma with 3% vacancy and no capex reserve, projecting an 8.9% cash-on-cash return. Graystone’s underwriting adjusted both assumptions to reflect real market data and revised the projected cash-on-cash return to 7.2%, and the deal still cleared the firm’s investment criteria at that conservative number. That kind of transparent revision before purchase is what separates a disciplined acquisition process from a sales pitch.
Managing more than 300 rental doors gives Graystone real operating data on an ongoing basis rather than modeled projections. That data closes the gap between pro forma and actual performance in a way that outside property managers often can’t replicate. In-house property management means the same team that underwrites each deal operates it, creating direct accountability for the numbers. For out-of-state investors, this structure significantly reduces the information gap that can make remote investing feel opaque. Investors should expect reporting that covers occupancy, rent collected, maintenance spend, and capital items on a regular basis, that kind of visibility is what keeps private real estate investment from feeling like a black box.
Putting it together: which path is right for your passive income goals
For investors who can tolerate illiquidity and take the time to evaluate deals properly, private real estate investment often offers greater tax flexibility and potentially more predictable current cash flow than REITs or stocks. The depreciation benefit, 1031 exchange deferral, and pass-through tax treatment create structural advantages that don’t exist in any publicly traded vehicle. But those advantages only materialize when the underlying deal is correctly underwritten. Apply the checklist: conservative vacancy, full expense load, realistic capex reserve, and a DSCR above 1.2x. If the numbers still work after that stress test, you have a deal worth pursuing seriously.
The strategy tier matters too. If you want current income from day one, core and core-plus private real estate is where to focus. If you can tolerate a longer hold with no early distributions in exchange for a higher target return, value-add deals make sense, provided the manager has the operational track record to execute. And private real estate isn’t right for every investor; if liquidity flexibility is a priority or the hold period doesn’t match your timeline, that’s worth working through before any capital moves.
For investors who want the returns of private real estate investment without managing every piece of the process, a full-service partner like Graystone Investment Group handles acquisition, conservative underwriting, transparent reporting, and in-house property management under one roof. That kind of end-to-end accountability is what separates strong private real estate investment outcomes from ones that looked good on paper and underdelivered in practice. Reach out to the Graystone team directly to walk through current Tampa market opportunities and see how a specific deal gets evaluated from first look through close.
Book an Expert
New investor? Start with Jorge.
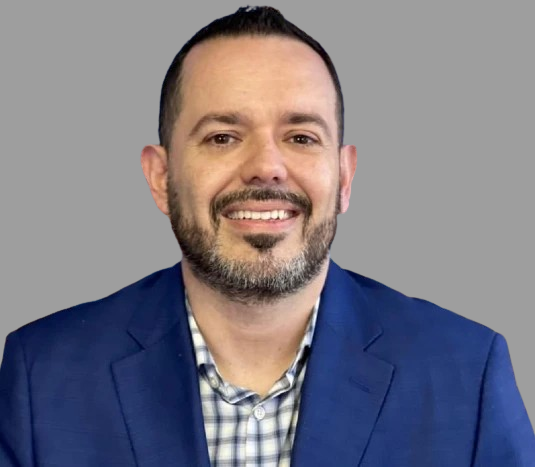
Jorge Vazquez – CEO & Investment Strategist at Graystone. Let’s make your portfolio stronger, steadier, and more profitable.
Deals? Book with Cody.
Meet Cody Bergstrom, Your Expert in Finding Deals Let’s find an off-market deal that actually works for you.
Need financing? Book with Lisa.
Meet Lisa Kaye Price, the LendingGig Top ML Let’s figure out the smartest way to fund your next deal.
Looking for PM? Book with Jay
Jay Michalec – COO & Property Management Expert at Graystone. Let’s make your rentals easier, calmer, and more profitable.